Estate planning
Why Your American Will Might Not Survive Your Move to Périgord
A will written in Ohio doesn't automatically travel with you into French succession law. Here is what actually happens to an American estate once Périgord becomes home — and the one clause that changes everything.
There's a particular moment that happens to almost every American couple who retires to rural France, usually a few years in, once the house is renovated, the neighbours know your name, and you've stopped thinking of yourselves as expats. Somewhere between your third vendange and your first serious conversation about what happens "after," a lawyer back home mentions, almost in passing, that your will might not mean what you think it means anymore.
What almost nobody realises in that moment is this: the will you signed in Ohio may already have been quietly overruled by a country you never asked to legislate your estate.
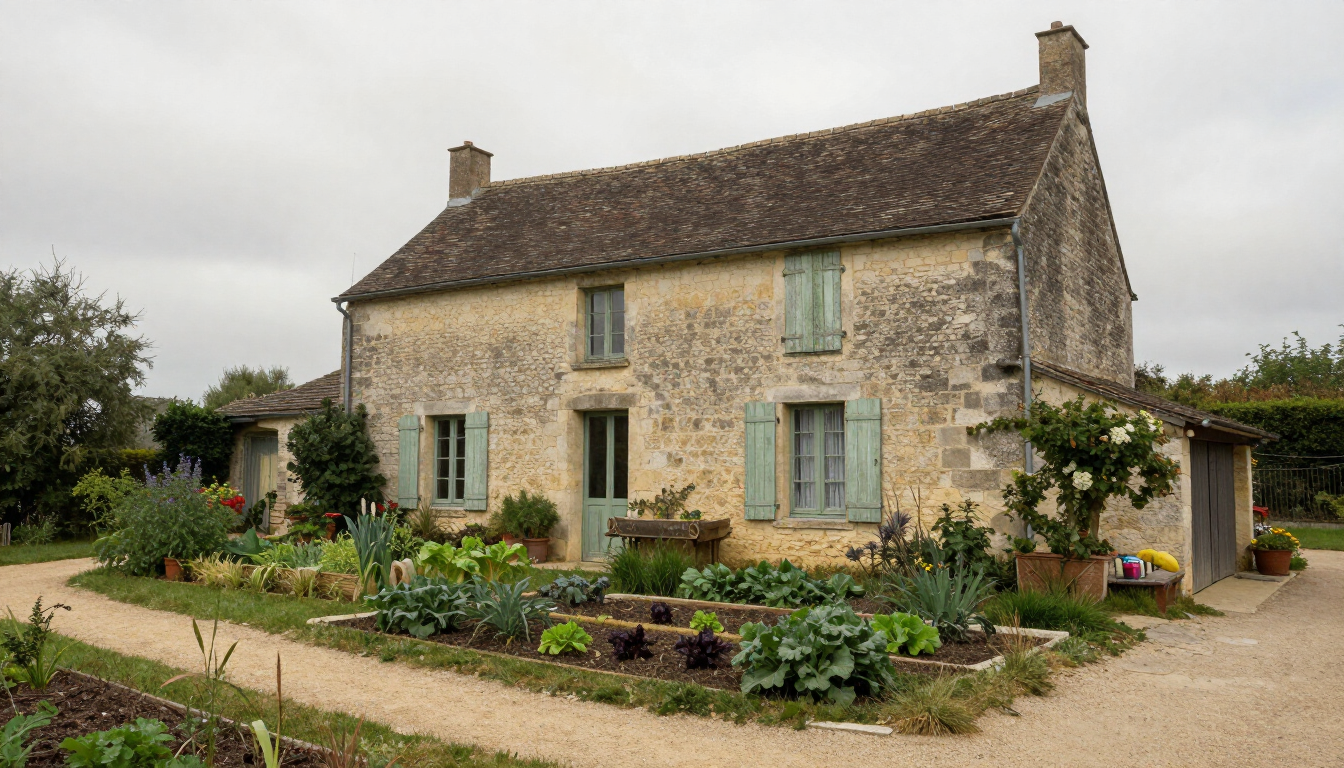
Mr and Mrs Doe are not real, but their situation is. They sold the house in Columbus, bought a stone farmhouse in the Périgord, and settled into the kind of retirement that fills postcards — market mornings, slow lunches, a garden that finally has room for everything they wanted to grow. Their two children stayed behind in Ohio, building careers and families of their own. The Does did what responsible people do: they wrote a will. An American will, drafted by an American attorney, under American law. It said what they wanted it to say — half of their financial assets to a cause they'd supported for decades, a US-based charity, and the French house to their children.
It is, on paper, a clean and generous plan. It is also, under French law, largely unenforceable as written.
The Clause Nobody Told Them to Include
Here is the part that catches Americans off guard almost every time: France does not ask what your will says first. It asks where you were actually living.
Since 2015, an EU regulation known informally as Brussels IV has governed how cross-border estates are handled across participating member states — and France applies it. Under its default rule, if you die habitually resident in France, your estate is governed by French succession law. Not the law of your citizenship. Not the law your will was written under. The law of the country where you were actually living.
There is an escape hatch. You are allowed to override that default by explicitly electing the law of your nationality in your will — a choice-of-law clause that names US law as the law governing your succession. It is a single paragraph. It costs nothing to include. And it is the one thing the Does never added.
Nobody told them to. And that single missing paragraph is the hinge on which their entire estate plan turns.
Why "Habitual Residence" Isn't a Technicality
It's tempting to assume this is a formality — surely a French court would recognise that two Americans, with an American will, intended American law to apply. It's a reasonable assumption. It's also not how the doctrine works in practice.
French courts look at where you actually lived your life: where your home base was, where your centre of economic and family interests lay, where you spent your time, where your daily routines and social ties were anchored. For a couple who have sold the house in Columbus, bought in the Périgord, registered with the local mairie, and been seeing a French doctor for three years, that finding is not a close call.
That finding isn't a side detail. It's the entire ballgame. Once a French court determines you were habitually resident in France, French succession law applies to your estate — regardless of what your American will says and regardless of what you intended.
The Rule That Reshapes the Plan: La Réserve Héréditaire
French law treats children differently than most American states do. Under the doctrine of la réserve héréditaire — forced heirship — a portion of your estate is reserved by law for your children and cannot be freely given away. This is not a tax. It is a substantive rule about who is entitled to inherit, and it overrides any contrary instruction in your will.
For two children, the math is unambiguous:
• Reserved share (la réserve): two-thirds of the estate, split between the two children — one-third each.
• Freely disposable share (la quotité disponible): the remaining one-third, the only portion you can leave to whomever you choose.
Their plan called for half of the financial assets to go to the US charity. French law permits that only up to the disposable one-third. Anything beyond it falls inside the children's reserved share and is theirs as of right — regardless of the will.
The house, at least, causes less friction on its face — leaving it to the children sits comfortably inside French expectations. But if its value alone doesn't cover their two-thirds entitlement, they can reach into the financial assets to make up the shortfall, tightening the charity's share even further.
The Tax Sting Hiding Behind the Legal One
Even the portion that does legally reach the charity doesn't necessarily arrive intact. Under French inheritance tax, gifts to non-relatives — and a US charity counts as a non-relative for these purposes — are taxed at the rate reserved for unrelated beneficiaries.
That means the transfer can be taxed at 60%, after any applicable relief has been applied. A generous legacy intended to support a cause the Does cared about for decades can arrive at the charity badly diminished — not because anyone was ungenerous, but because the plan was never built for the tax environment it ended up in.
What Actually Fixes This
None of this means the Does' wishes are impossible. It means the plan they have isn't built for the legal environment they're now living in. A few tools, used deliberately and in advance, change the outcome substantially:
• An explicit choice-of-law clause. Naming US law under Brussels IV's nationality election keeps the estate under American succession rules, where the Does can freely leave their assets as they wish — including the charitable gift.
• Assurance vie. French life-insurance contracts sit outside the estate for forced-heirship purposes: the beneficiary designation overrides the réserve, and the capital passes directly to the named beneficiary.
• Lifetime giving. Making the charitable gift while alive, rather than through the estate, sidesteps the succession rules altogether — provided the Does are comfortable parting with the funds now rather than later.
Each of these has trade-offs, and none of them is a document you draft alone on a Sunday afternoon.
Before You Sign Anything
The lesson here isn't "don't retire to Périgord," and it isn't "don't support the causes you care about." For most American retirees, the whole appeal of this move — the slower rhythm, the stone walls, the market on Saturday — has nothing to do with succession law, right up until the day it has everything to do with it.
The real lesson is that a will written for one legal system doesn't automatically travel with you into another. That question needs answering while you're still the one asking it — not left for your children and a French court to sort out later, on a timeline and under rules you never chose.
This is exactly the kind of situation where a US will and a good intention aren't enough on their own. Before finalising — or revisiting — an estate plan that spans France and the US, it's worth sitting down with a notaire who handles cross-border successions and a lawyer familiar with both French forced heirship and the US-France tax treaty. It's not an extra formality. It's the difference between a plan that works exactly as intended, and one that quietly rewrites itself the day you're no longer there to explain what you meant.
Legal Note
This article is provided for general informational purposes and does not constitute legal or tax advice. Cross-border succession rules, the application of Brussels IV, French forced-heirship provisions, and inheritance tax rates are complex and subject to change. Always consult a qualified notaire and a lawyer familiar with both French and US estate law before making any decisions about your estate plan.
France Made Easy works with a network of specialised professionals to guide you through each of these steps.
Sources
- Cross-border inheritance France — Global Law Experts
- French Inheritance Laws for US Citizens — LegalClarity
- Brussels IV and Choice of Law: Can You Bypass French Forced Heirship? — Advocate Abroad
- French Inheritance Law for Americans — EasyFranceNow
- Forced Heirship in France: What US and UK Families Must Understand Before Relocating — Bespoke Tax
- Forced Heirship by Country — The Citizenship Desk
- Inheritance and Property in France: What Expatriates Need to Plan For — Home Select Paris
- French Inheritance Law for Foreign Owners 2026 — La Reserve
- French Inheritance Tax Guide for US Expats — Taxes for Expats
- French Inheritance and Gift Tax for US Citizens — Expat Filings
- Brussels IV: Choosing Your National Law for Your French Estate — French Business Law
You might also find helpful
Need help navigating France?
We guide buyers and newcomers through every step — from property search to administrative set-up.
Book a free consultation · See all services